 RePerspective Labs
INSIGHT
Playbook
From Idea to Operating Case: Building the Business Case for Automation-to-Autonomy
Connect the promise of automation and AI to the work, ownership, and evidence required to deliver sustainable value.
Executive summary
Automation and AI proposals become credible when projected benefits are tied to changes the business can implement and sustain. An operating case makes the required work, costs, ownership and authority explicit within the business case. It matches funding to evidence: discovery tests the opportunity, a trial tests operating assumptions, and expansion depends on demonstrated value and control. After deployment, the case must show which decision converted released capacity into accepted outcomes, what explains the improvement, and whether it persists. Better service can justify additional expense without producing cash savings. The objective is a justified next commitment, with a clear basis for changing course.
The question
What are we actually approving?
An investment review can be full of numbers yet leave consequential assumptions unstated. Hours saved are valued at salary rates, although no spending will fall. Human review is described as a safeguard, although nobody has estimated its workload. A successful demonstration becomes grounds for rollout before the people expected to run it have helped shape the operation.
Each gap makes the proposed return conditional on a decision still unmade. Together, they can turn an apparently attractive investment into a commitment the business is unprepared to fulfill.
The same problem may also support very different responses: simplify the process, automate stable rules, assist a person’s judgment, or delegate a bounded decision. Those choices carry different costs and responsibilities.
Once a problem has been selected, the executive question becomes: what must be true for this particular solution to deliver value, and how much commitment does the available evidence justify?
My perspective
I would fund an automation or AI initiative only at the level its evidence can support. After deployment, I would require the Outcome owner to show which operating decision converted capacity into accepted results, at what full cost, and whether those results persisted. That evidence should guide Expand · Continue · Narrow · Redesign · Stop. Greater autonomy needs its own justification.
Shashi Sethi
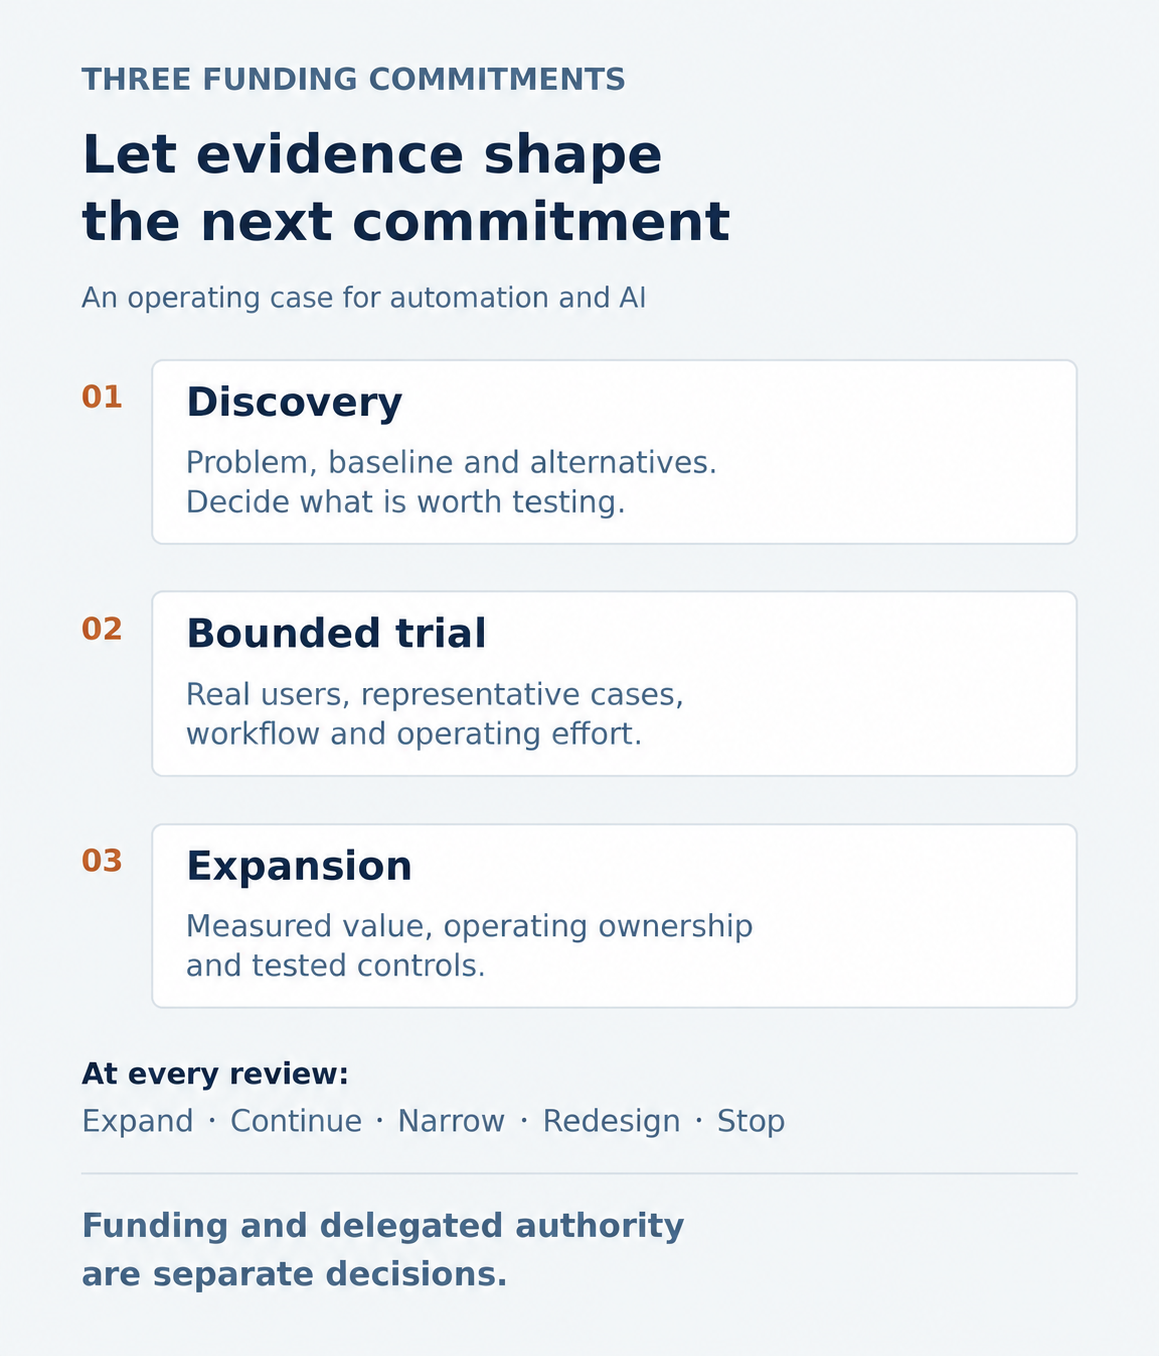
Evidence should justify the next commitment. Funding and delegated authority remain separate decisions.
The approach
Make the operating logic part of the investment decision
A rigorous business case already considers more than financial return. HM Treasury’s Green Book, updated February 5, 2026, describes a management case covering implementation, governance, change management, benefits realization, risk, and evaluation. Operating discipline belongs inside established investment practice. HM Treasury: The Green Book, Five Case Model.
I use operating case to describe the explicit connection between the investment forecast and how the business will work. It can sit within the existing approval document. Its purpose is to expose the assumptions that determine whether the return is achievable.
Start with the outcome and its current constraint. Faster document preparation has limited value if an unchanged approval queue still determines when customers receive a decision. Removing a handoff may create more value than accelerating it.
Compare credible alternatives against the same outcome, baseline, and time horizon. Include the current approach, process simplification, conventional automation, and AI where appropriate. This is where the problem-selection work in The Value Lens becomes a specific investment choice.
When proposing autonomy, explain what additional value comes from allowing the system to act. Then account for the additional assurance, monitoring, and recovery it requires. A useful recommendation tool may be the right destination for a particular decision.
Explain how the benefit will become real
Every benefit in the forecast needs an operating change that makes it possible and an owner who can realize it.
Released time creates usable capacity when it can be consolidated or reassigned. That capacity produces value when needed work gets done or service improves. Cash savings arise when an identifiable expense falls. Better service becomes measurable when customers receive a more timely or reliable outcome. These benefits deserve separate measures.
Research illustrates why a productivity finding cannot simply become a standard savings assumption. In a study published in February 2025, Brynjolfsson, Li, and Raymond examined 5,172 customer-support agents during an AI-assistance rollout concentrated in late 2020 and early 2021. Access to the assistant increased issues resolved per hour by 15% on average, with substantial differences across workers. This was evidence from one firm’s support operation and its contractors, where people retained authority over responses. Generative AI at Work.
My implication for investment reviews is straightforward: use external evidence to shape a local test. It cannot establish your realizable savings or justify autonomous action in a different workflow.
The Outcome owner commits to the accepted result, its service and quality thresholds, and the resources needed to achieve it. The Operating owner changes assignments, queue priorities, staffing allocation and handoffs to make that commitment workable. If a service promise or downstream team must change, the person with that authority must agree; the Sponsor resolves barriers beyond the owners’ remit. Redesigning Work Around Outcomes develops this connection between the result and the work.
If the aim is to absorb demand without additional hiring, identify the demand forecast, the staffing decision, and when the avoided expense would otherwise arise. If the aim is better service, track completed outcomes, waiting time, and rework. Finance challenges the benefit evidence and its financial interpretation; the Outcome owner remains accountable for realizing the result.
Workforce design is part of this logic. Involve the people doing the work in identifying hidden checks and difficult exceptions. Budget for learning and changes to responsibilities. If routine work falls away, the remaining workload may require more judgment per case; staffing it solely from average handling time can leave the operation exposed at peak demand.
Give those people time and authority to challenge outputs, resolve exceptions, and improve the process. A benefit forecast that assumes this contribution must also resource it.
Price the operation that will deliver the return
The relevant cost is the cost of delivering the outcome over the chosen period. Include preparation and integration, knowledge maintenance, user transition, human review, technology consumption, support, evaluation, and incident recovery.
Separate initial expenditure from recurring costs, and show when benefits are expected to begin. Test a downside case with slower adoption, fewer eligible cases, and more review effort. Those assumptions should change the forecast rather than sit in a risk appendix.
The control model also changes the economics. If a system needs authoritative policy content to work, maintaining that content is an operating expense. If it may take consequential action, monitoring and intervention capacity are part of the service being funded.
NIST’s voluntary AI Risk Management Framework includes post-deployment monitoring, user feedback, override, incident response, recovery, and decommissioning. These are useful reference points when estimating what continued operation requires. NIST AI RMF 1.0, MANAGE 4.1, January 26, 2023.
Shared foundations deserve explicit treatment too. Where several initiatives need the same knowledge service or monitoring capability, show the common investment and how its costs are allocated. Record each dependent initiative’s incremental costs and benefits. Count the shared cost once in the consolidated portfolio, and distinguish committed reuse from speculative future demand.
For the running operation, use Cost per accepted outcome:
Total recurring cost of running the capability in a period ÷ outcomes accepted by the owner in that period.
Include technology and usage, human review and correction, exception handling, support and recovery. Failed and repeated attempts count in costs, not as additional accepted outcomes. Keep one-time build costs in the investment case, outside this operating metric. Match scope and measurement periods, including the acceptance follow-up. With zero accepted outcomes, the metric is not calculable.
A worked example: invoice exceptions
Hypothetical illustration. All figures below are assumptions for testing, not measured results or a forecast for a particular organization.
Suppose a finance operation handles 400 invoice exceptions each week, averaging 15 minutes of staff effort per case. The objective is to reduce the aging backlog while preserving payment controls.
The proposal would assemble relevant records and approved policy guidance for analysts. People would continue to decide resolutions; payment approval and supplier bank-detail changes would remain outside the system’s authority.
| Assumption | Implication |
|---|---|
| Current work: 400 cases × 15 minutes | 100 staff hours per week |
| 240 cases are suitable for assistance and use it | 60% of weekly volume |
| Assisted cases take 9 minutes, including checking and corrections | 6 minutes potentially released per assisted case |
| Remaining 160 cases stay at 15 minutes | 40 hours of unchanged work |
| Additional monitoring and knowledge maintenance require 4 hours weekly | Proposed total effort becomes 80 hours per week |
| Net reduction: 100 − 80 hours | 20 hours of potential weekly capacity |
The arithmetic is conditional on suitability, actual use, and review effort. If only 120 cases benefit, with the same time reduction and overhead, the potential gain falls to eight hours per week. Test those assumptions before annualizing them.
Suppose the analyst team remains the same size and its employment costs do not change. The table supports a capacity hypothesis. A cash-saving claim would need a separate change in expenditure.
The Operating owner for finance operations must decide how that capacity will reduce backlog, then measure whether it does. A trial should compare similar cases with and without assistance, including total handling time, resolution quality, repeat work, backlog age, and staff review effort. Match the comparison for case complexity and workload; include peak periods and difficult exceptions.
No payback claim follows from this illustration: implementation costs, ongoing technology costs, benefit timing, and any realizable cash benefits still need to be established.
The result may justify wider use of assistance. Delegating exception clearance would require additional evidence about decision quality, boundaries, and recovery, alongside a fresh assessment of value.
Following the capacity into an accepted outcome
Extend the illustration with a six-week reporting period. All costs and results that follow are hypothetical. Routine arrivals remain at 400 a week. Separately, 400 aged exceptions await resolution because purchasing confirmations arrive too slowly. The Outcome owner judges this overdue service a priority: suppliers need reliable decisions about their invoices. Before starting, the owner agrees to spend up to an additional $2,400 over six weeks to secure at least 120 accepted aged resolutions, while maintaining routine service and payment controls.
Assume local measurement confirms the net 20 hours released each week. The Operating owner assigns that capacity to aged cases and agrees a daily confirmation slot with the purchasing manager, who reallocates existing staff time. Assume no additional overtime or displaced purchasing commitments. An aged case requires 30 minutes of total staff effort, including confirmation, correction and acceptance follow-up. Four weeks’ released capacity therefore supports 20 × 4 ÷ 0.5 = 160 aged cases. That is calculated capacity; it establishes no accepted outcome.
Acceptance requires a documented, correct resolution, confirmation by the receiving team, and no reopening during ten business days of follow-up. The routine effort estimates also include case-level follow-up; the four weekly monitoring hours remain separate. The Operating owner must verify that these demands fit within funded capacity.
At week 6, suppose the register confirms 160 accepted overdue resolutions, with routine service protected and additional spending within the $2,400 limit. The owner’s minimum of 120 has been exceeded. That is the reason to fund this service improvement. There is no demonstrated cash saving or avoided hiring: better service can represent realized value without cash savings. Whether it remains worth funding depends on the next review and the alternatives.
Six-week case reconciliation — hypothetical
| Case stream | Opening position and inflow | Accepted by week 6 | Still unaccepted at close |
|---|---|---|---|
| Routine | 800 awaiting follow-up at opening; 400 × 6 = 2,400 new arrivals. | 800 opening cases + 1,600 handled in weeks 1–4 = 2,400. | 800 handled in weeks 5–6, pending follow-up. |
| Aged | 400 unresolved cases; no routine cases newly enter this queue. | 160 handled in weeks 1–4, with follow-up completed. | 400 − 160 = 240: 80 pending follow-up and 160 awaiting resolution. |
Pending cases earn no benefit credit. An equivalent comparison queue, with comparable demand and case mix, is assumed to maintain routine service but make no progress on its aged backlog.
| Recurring cost assumption | Six-week cost |
|---|---|
| Existing operation: $6,000 weekly, including unchanged employment costs, allocated purchasing effort and existing support | $36,000 |
| Additional technology and usage: $300 weekly | $1,800 |
| Additional support and recovery: $100 weekly | $600 |
| Total: $36,000 + $1,800 + $600 | $38,400 |
These assumptions include all six weeks of review, correction, monitoring, knowledge maintenance and follow-up, including work on cases still pending. Remaining follow-up enters the next period’s operating cost; outcomes count only when accepted. Existing payroll already covers the reassigned hours; do not add them again as a new expense. One-time build costs remain outside this table.
Cost per accepted outcome = $38,400 ÷ (2,400 routine + 160 aged) = $15.00. This is a period measure across two case types, not evidence that routine and aged cases cost the same. Keep their volumes, effort, waiting time and quality visible separately.
The financial effect is $1,800 + $600 = $2,400 more recurring expenditure over six weeks. The accepted service improvement is the benefit being purchased.
If the same 20 hours remain unassigned, or purchasing confirmations still block resolution, the calculation produces no additional accepted outcomes. With service otherwise unchanged, the additional expense has bought no realized benefit. Faster preparation alone has not removed the remaining constraint.
Verify the benefit after deployment
An accepted outcome shows what happened. Attribution asks how much of that change resulted from the intervention. HM Treasury’s Magenta Book, updated May 2026, distinguishes tracking benefits from evaluating their causes, unintended effects and additional impact against a counterfactual. That distinction matters in an operating review.
Agree the baseline and comparison before the change. Keep the same scope, acceptance rules and observation window; record arrivals, case complexity, opening backlog and pending acceptance at both ends. Compare similar cohorts or use a staged rollout where feasible. Examine staffing, overtime, seasonality, policy changes and other improvements that could explain the result. Report uncertainty when a credible comparison is unavailable.
In the invoice example, the claim concerns AI assistance combined with reassignment and faster purchasing confirmations. It does not isolate AI’s contribution. Testing the same operating redesign without AI would help establish whether the technology earns its additional cost.
Finance should reconcile the claim to operating records and expenditure, challenge the counterfactual, and distinguish service improvement from cost avoidance and realized cash savings. Cost avoidance needs evidence of spending that would otherwise have occurred; cash savings need an actual expense reduction, net of additional costs. The Government Efficiency Framework provides a useful public-sector reference for evidence, sustainability and avoiding duplicate savings claims. The Outcome owner still decides whether the accepted service result warrants the resources.
Keep one claim linked to unique case records. The hours reassigned to backlog reduction cannot also become salary savings or support another allocation claim. Where several teams contribute to one improvement, reconcile their records before consolidating the benefit.
Check retention after normal operations resume—for example, at weeks 8 and 12. Examine reopenings, new aging, routine service, downstream waiting, receiving-team effort, support costs and control failures. A gain maintained through hidden overtime or transferred delay needs reassessment. Clearing a finite backlog is not a benefit to multiply indefinitely: once it is cleared, decide how the capacity will be used next.
Match the next commitment to the evidence
An early idea does not need a fully proven operating model to earn discovery funding. It needs a worthwhile question, a bounded cost, and a test capable of changing the next decision.
Use the operating case to state exactly what is being approved.
| Commitment | Evidence the next review should examine |
|---|---|
| Fund discovery | Is the problem material, what is the baseline, and which alternatives merit testing? |
| Fund a bounded trial | Does the proposed workflow work with real users, representative cases, explicit boundaries, and accounted-for operating effort? |
| Fund expansion | Do measured outcomes, costs, operating ownership, and tested controls support the proposed scope? |
For each commitment, specify the spending limit, permitted scope, Outcome owner, review date, and conditions for stopping or changing course. Set success and failure criteria before the results arrive.
Funding and delegated authority should be separate decisions. Expanding an assistant to more users does not automatically justify letting it approve transactions. Equally, an operation can create material value while keeping consequential decisions with people.
After deployment, use the benefit evidence and retention checks at scheduled reviews, and revisit the case when costs, demand, policy, system behavior or scope changes enough to affect its assumptions. Choose Expand · Continue · Narrow · Redesign · Stop, and record the evidence needed for the next decision.
Keep one concise operating-case canvas
Retain a one-page executive view, supported by the evidence needed for the decision. At the top, name the approval sought, funding requested, scope, and next review date.
| Canvas element | What the case should make explicit |
|---|---|
| Strategic outcome | The enterprise priority, current baseline, target, and time horizon. |
| Operating problem | The constraint being addressed and the cost or consequence of leaving it unresolved. |
| Work and decision scope | What changes, affected handoffs, and decisions that remain human-owned. |
| Solution choice | Alternatives considered and why the proposed level of automation or autonomy is justified. |
| Knowledge and dependencies | Required sources, their owners, readiness gaps, and funded enabling work. |
| Governance boundaries | Permitted actions, exclusions, escalation, intervention, and evidence of control. |
| People and ownership | Outcome owner, changed roles, transition effort, support capacity, and running budget. |
| Value and learning | How benefits will be realized, full costs, uncertainty, evaluation method, and conditions for expanding or stopping. |
Mark assumptions as assumptions and measured results as results. Give each material uncertainty an owner and a means of resolving it.
Carry each material benefit into review through the existing case, using a compact record linked to its evidence:
| Benefit-review record | What to retain |
|---|---|
| Outcome and acceptance | Intended result; owner’s acceptance criteria and service safeguards. |
| Comparison | Baseline, scope, cohort, period, demand, case mix and counterfactual. |
| Capacity and decision | Net capacity verified; authorized allocation and remaining constraint. |
| Responsibilities | Outcome owner; Operating owner and receiving-team commitments; Finance validation. |
| Operating cost | Full recurring cost, allocation basis and matched accepted count; separate build investment. |
| Benefit and evidence | Service improvement, cost avoidance or cash savings; supporting records. |
| Claim limits | Attribution uncertainty; unique case and benefit references; duplicate-claim checks. |
| Retention and decision | Follow-up dates, persistence and displaced-burden checks; next formal review decision. |
Within the Transformation Operating Map, the initial operating case remains a Frame the Opportunity discipline. Carrying its commitments into review connects the original investment decision to evidence from the running operation.
Leadership takeaway
Before the next funding decision
Bring the Sponsor, Outcome owner, Operating owner, Finance partner, and a representative of the people doing the work into the same review. Ask them to trace the largest proposed benefit from the current baseline through the changed work to the outcome the business will actually realize.
Where the explanation breaks, identify the missing decision or evidence. A gap in knowledge quality may justify preparation work. An uncertain benefit may justify a bounded trial. An unresolved owner or unmanageable control burden may require a narrower proposal.
Then record the next commitment: what is funded, what the system may do, who is accountable, and what result would change the decision. For a deployed capability, ask which outcomes have been accepted, what explains the improvement, and when its persistence will be checked.
The useful test is whether the people responsible for delivering the return can explain how they will do it—and have the resources and authority to follow through.
Sources and further reading
- HM Treasury — The Green Book (2026), February 5, 2026. Established appraisal and business-case discipline, including the management case.
- Erik Brynjolfsson, Danielle Li, and Lindsey R. Raymond — Generative AI at Work, published February 4, 2025; The Quarterly Journal of Economics, May 2025 issue. Evidence of productivity differences during an AI-assisted customer-support rollout.
- National Institute of Standards and Technology — Artificial Intelligence Risk Management Framework (AI RMF 1.0), January 26, 2023. See MANAGE 4.1 for post-deployment monitoring, intervention, incident response, recovery, and decommissioning.
- HM Treasury and Evaluation Task Force — Magenta Book: Central Government guidance on evaluation, updated May 15, 2026. Section 1.7.1 distinguishes benefits management from evaluation, including counterfactuals and attribution.
- Government Finance Function and HM Treasury — The Government Efficiency Framework, updated November 24, 2025. Sections 4.4–4.5 address evidence for cash-releasing and non-cash-releasing benefits; its reporting context is UK government.